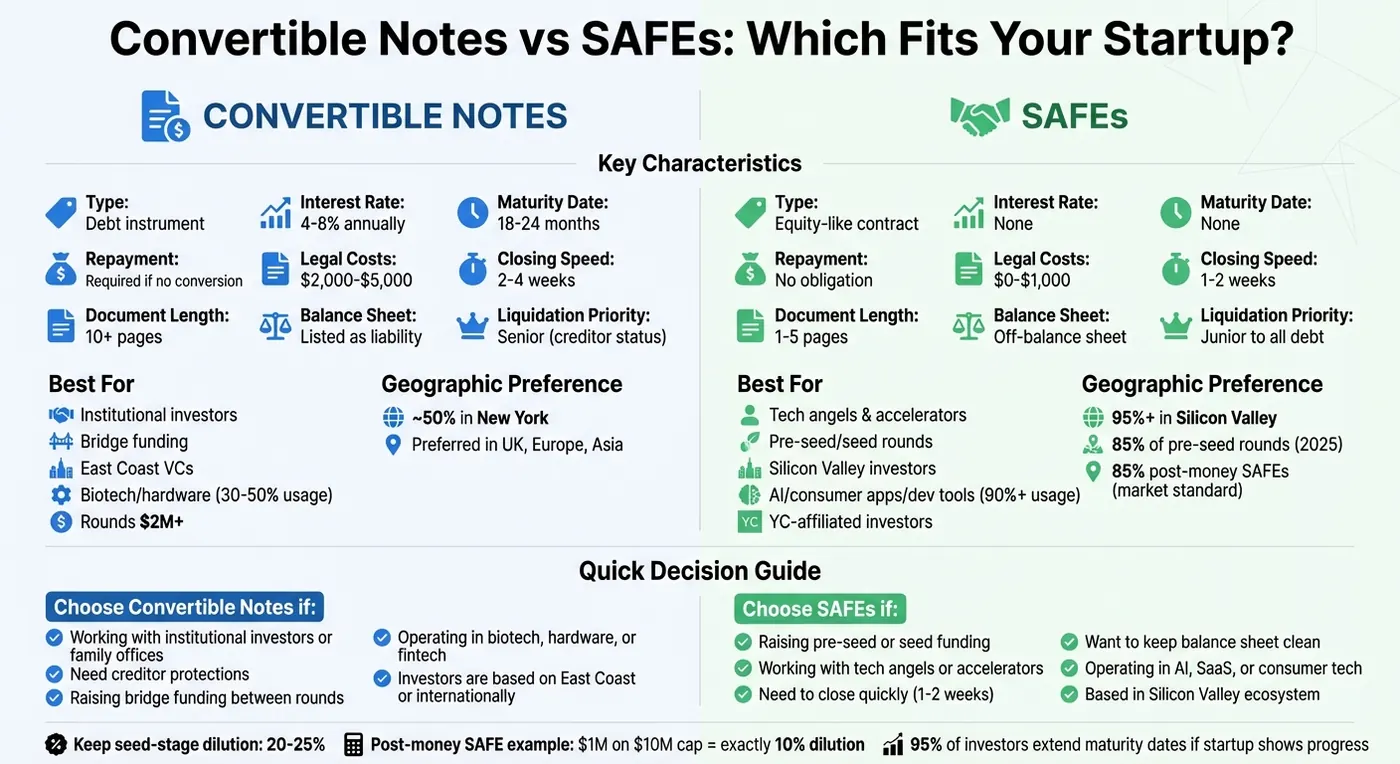
Choosing between Convertible Notes and SAFEs depends on your startup's needs and investor preferences. Both tools simplify early-stage fundraising by delaying formal valuation, but they work differently.
- Convertible Notes: Structured as debt with interest (4–8%) and a maturity date (18–24 months). They convert to equity during a qualified financing round or can require repayment. Notes prioritize investor protections but add balance sheet liabilities.
- SAFEs: Equity agreements without interest, maturity dates, or repayment obligations. They’re faster, cheaper, and simpler to execute, favored by tech angels and accelerators. SAFEs dominate in Silicon Valley but may lead to higher dilution.
Quick Overview:
- Convertible Notes: Best for institutional investors, bridge funding, or industries like biotech.
- SAFEs: Ideal for pre-seed/seed rounds, especially with tech-focused investors.
Quick Comparison:
| Feature | Convertible Note | SAFE |
|---|---|---|
| Type | Debt | Equity-like contract |
| Interest | 4–8% annually | None |
| Maturity Date | Yes (18–24 months) | None |
| Repayment Obligation | Yes | None |
| Speed | Slower (2–4 weeks) | Faster (1–2 weeks) |
| Cost | $2,000–$5,000 | $0–$1,000 |
| Investor Appeal | Institutional | Tech angels, accelerators |
Key Takeaway: Match the funding instrument to your timeline, investor type, and industry. Convertible Notes offer structure and protections, while SAFEs prioritize simplicity and speed.
Convertible Notes & SAFEs: Which One to Choose?
What Are Convertible Notes?
A convertible note is essentially a short-term loan that turns into equity when your startup undergoes its next priced funding round. The loan amount, along with any interest that has accrued, converts into equity during this round.
One of the main advantages? You can raise funds without having to assign a valuation upfront. This means you can delay those tough valuation discussions until your business has gained more traction, customers, or revenue - factors that can justify a higher valuation per share.
Since convertible notes are structured as debt, they come with legal obligations that aren't present with SAFEs (Simple Agreements for Future Equity). If your startup doesn’t hit a priced round by the note’s maturity date (usually 18–24 months), you’ll need to repay the money. This maturity date ensures that conversion happens within a set timeframe.
Another key point: in case your startup dissolves or is acquired before the note converts, convertible note holders are prioritized over SAFE holders and common shareholders. In other words, they get paid first.
Key Features of Convertible Notes
Convertible notes come with specific financial terms that determine how and when the debt converts into equity. Here’s a breakdown:
- Principal Amount: This is the initial investment amount, which serves as the starting point for all future calculations.
- Interest Rate: Convertible notes usually come with an annual interest rate of 4%–8%. The interest accrues over time and is added to the amount that converts into equity.
- Maturity Date: This is the deadline - typically 18 to 24 months from when the note is issued. By this date, the note must either convert to equity, be repaid in cash, or get an extension. Interestingly, about 95% of investors are willing to extend the maturity date if the startup is making progress.
- Valuation Cap: This sets a maximum valuation for the note’s conversion. For example, if your Series A valuation is $15 million but the note has an $8 million cap, the note converts based on the $8 million valuation. This gives early investors a larger share of equity.
- Discount Rate: This provides a percentage discount (usually 15%–25%) on the share price paid by new investors. For instance, if Series A investors pay $1.00 per share, note holders with a 20% discount pay $0.80 per share.
These terms define how and when the notes convert into equity during a triggering event.
How Convertible Notes Work
Convertible notes typically convert during a Qualified Financing - a priced equity round where the startup raises a minimum amount, often between $500,000 and $1 million. Another trigger is a Change of Control, such as an acquisition or IPO. In these cases, the note either converts into equity just before the transaction or results in a cash payout of 1x–2x the principal.
When it’s time to convert, investors use the method - either the valuation cap or the discount - that gives them the lower share price.
Here’s an example: A startup raises $1 million through a convertible note with a 6% interest rate and an $8 million valuation cap. After 15 months, the startup raises a Series A at a $15 million valuation. Since the cap provides a better deal, the note converts at the $8 million valuation. With $75,000 in accrued interest added, the note holder ends up with 1,343,750 shares, equating to 13.4% ownership. This is a much larger stake than they would have received at the higher Series A valuation.
Because convertible notes are classified as debt, they convert before SAFEs and new equity investments. This prioritization is crucial for cap table calculations and minimizing founder dilution.
What Are SAFEs?
A SAFE (Simple Agreement for Future Equity) is essentially a contract that gives investors the right to receive equity in a startup at a later date. Unlike a loan, it doesn’t come with repayment obligations. Y Combinator introduced SAFEs in 2013 to simplify the complexities and high legal costs of traditional funding methods.
Here’s how SAFEs differ from convertible notes: they don’t have interest rates, maturity dates, or repayment requirements. Instead of acting as debt, SAFEs grant investors the right to own equity when a specific event occurs, such as the startup’s next priced funding round.
Because they aren’t considered debt, SAFEs don’t show up as liabilities on a company’s balance sheet. This can make financials look cleaner, which is helpful when applying for loans, grants, or credit lines. By 2025, more than 85% of pre-seed funding rounds were conducted using SAFEs, making them the go-to option for early-stage startups.
"The beauty of SAFEs is speed. There's no negotiation over interest rates, maturity dates, or conversion mechanics - the terms are standardized." - Michael Kaufman, Founder & Editor-in-Chief, VC Beast
Another advantage of SAFEs is their role in high-resolution fundraising. This approach allows startups to close deals with individual investors on a rolling basis, each potentially with different terms, rather than waiting to finalize an entire funding round. This means founders can access funds as soon as an investor commits, rather than enduring lengthy delays.
Key Features of SAFEs
SAFEs are simpler than convertible notes, which is one reason they’re so popular. Here are some key features:
- Valuation Cap: This sets a maximum valuation at which the SAFE converts into equity. For example, if your Series A round values your company at $15 million but your SAFE has an $8 million cap, the SAFE converts at $8 million. This gives early investors more shares for their initial investment.
- Discount Rate: SAFE holders often receive a discount (typically 15%–25%) on the share price paid by new investors. For instance, if Series A investors pay $1.00 per share and the SAFE has a 20% discount, holders would pay $0.80 per share.
- Post-Money vs. Pre-Money: The post-money SAFE has become the standard, with 85% market adoption since its introduction in 2018. Post-money SAFEs provide clarity on ownership percentages at the time of signing.
- Pro-Rata Rights: Some SAFEs grant investors the option to maintain their ownership percentage in future funding rounds. Interestingly, 61% of SAFEs include only a valuation cap, while 30% offer both a cap and a discount.
Unlike convertible notes, SAFEs don’t accrue interest or have a set deadline for conversion or repayment. Legal costs for a SAFE round are also much lower - around $2,000 to $5,000 compared to $15,000 to $30,000 for a priced round.
How SAFEs Work
SAFEs convert into equity when specific trigger events occur. The most common trigger is an equity financing round, such as a Series Seed or Series A. In these cases, SAFE holders receive the same class of preferred stock as new investors.
Another possible trigger is a liquidity event, like an acquisition or IPO. If this happens, SAFE holders typically receive either their original investment back or the value of the shares they would have received upon conversion - whichever is higher. In the event of a company shutdown, SAFE holders are paid after creditors but before common stockholders.
For example, in November 2025, Sarah Martinez, the founder of TechStart, raised $500,000 using a SAFE with a $4 million valuation cap and a 20% discount. Six months later, her company closed a $2 million Series A at a $10 million pre-money valuation. Thanks to the $4 million cap, SAFE investors converted at a better rate than the discount alone would have provided. This approach also kept her balance sheet clean, which helped her secure a $100,000 government grant.
Main Differences Between Convertible Notes and SAFEs
Understanding the differences between convertible notes and SAFEs is key to navigating how each affects your startup's financial and legal framework.
The biggest distinction lies in their classification: convertible notes are debt instruments, while SAFEs function as rights to future equity. This difference impacts not only your balance sheet but also how investors are treated if the company faces financial troubles. Founders need to consider how these instruments influence speed, cost, and control during early fundraising strategies.
Convertible notes come with an interest rate, typically ranging from 4–8% annually, and a maturity period of 18–24 months. This means they accrue interest over time, potentially leading to greater dilution when converted to equity. In contrast, SAFEs have no interest or maturity date, making them simpler to manage. When a convertible note matures, it must either convert into equity, be repaid, or renegotiated, adding a layer of complexity.
Another key difference is how these instruments convert. SAFEs generally convert during any priced equity round, regardless of its size. Convertible notes, however, often require a "Qualified Financing" event, such as raising at least $1 million, to trigger their conversion. If both instruments are in play, convertible notes convert first because they are classified as debt.
From a legal and financial perspective, SAFEs are simpler and cheaper to execute, involving fewer pages and lower legal fees. Convertible notes, being debt instruments, are recorded as liabilities on your balance sheet, which can affect your ability to secure additional funding. SAFEs, on the other hand, do not create this issue.
Feature Comparison Table
| Feature | SAFE | Convertible Note |
|---|---|---|
| Instrument Type | Equity-like contract (warrant) | Debt (loan) |
| Interest | None | 4–8% annually (2026 market) |
| Maturity Date | None | 18–24 months typical |
| Repayment Obligation | No obligation | Must repay or renegotiate at maturity |
| Balance Sheet | Not recorded as debt | Recorded as a liability |
| Liquidation Priority | Subordinate to creditors | Generally prioritized over SAFE holders |
| Legal Complexity | Low (1–5 pages, legal fees ~$0–$1,000) | Moderate–high (10+ pages, legal fees ~$2,000–$5,000) |
| Tax Complexity | Minimal | Higher (due to interest tracking and deductibility) |
This breakdown provides a solid foundation for evaluating the pros and cons of each funding option in the next sections.
Pros and Cons of Convertible Notes
Benefits of Convertible Notes
Convertible notes come with some appealing advantages, particularly for institutional seed funds and family offices. One standout feature is their creditor status, which gives noteholders priority during liquidation. This structure can help reduce risks for investors.
Another big plus is the maturity date, which creates a sense of urgency. This can be a game-changer for startups. For instance, Airbnb used convertible notes early on to set a timeline that pushed them to wrap up their Series A round faster. This built-in deadline helps both founders and investors stay on track with a clear schedule.
Bridge funding is another strong point. Convertible notes usually close quickly - often within 2–4 weeks. This makes them a great option for raising capital between major funding rounds without getting bogged down in lengthy negotiations. In fields like biotech and hardware, where development timelines are long and require structured protections, convertible notes are used in 30–50% of early-stage rounds.
In places like New York and Boston, where traditional VC practices dominate, convertible notes can also align better with local investment norms.
Still, while these benefits are attractive, the structure of convertible notes also comes with some challenges.
Drawbacks of Convertible Notes
Despite their benefits, convertible notes have some notable downsides that founders need to consider.
Since they are debt instruments, convertible notes add liabilities to your balance sheet, which can complicate future borrowing. On top of that, the interest they accrue leads to more dilution. Interest rates have risen significantly - 4–8% in 2026 compared to 2–4% in 2021 - and this accrued interest converts into additional shares. The maturity date can also create stress. If your startup hasn’t hit a qualifying priced round by then, you could face tough choices like renegotiation or repayment.
"The maturity date creates a forcing function - if you haven't raised a priced round by maturity, you technically owe the money back." – Michael Kaufman, Founder & Editor-in-Chief, VC Beast
Another issue is the legal complexity. Drafting convertible note agreements often involves more than 10 pages of documentation and legal fees ranging from $2,000 to $5,000. By comparison, SAFEs (Simple Agreements for Future Equity) are simpler, with legal costs typically between $0 and $1,000. Negotiations for convertible notes also take longer - usually 2–4 weeks versus 1–2 weeks for SAFEs. This extra time can delay your ability to put the funds to work. To navigate these complexities, it’s crucial to work with startup lawyers familiar with details like side letters and most-favored-nation clauses.
Lastly, the qualified financing threshold can be a hurdle. Most convertible notes only convert into equity if your next funding round meets a minimum amount - often $1 million or more. If you raise less than that, the note doesn’t convert and remains as debt, leaving you with a repayment obligation instead of equity.
Ultimately, founders need to carefully weigh these pros and cons to decide if convertible notes fit their fundraising goals and long-term strategy.
Pros and Cons of SAFEs
Benefits of SAFEs
SAFEs (Simple Agreements for Future Equity) have gained popularity in early-stage fundraising due to their efficiency and ease of use. These agreements are concise, typically spanning just 1–5 pages, and can be finalized in as little as 1–2 weeks. This rapid turnaround makes them significantly faster than traditional convertible notes.
One of the standout features of SAFEs is that they don’t create debt obligations. Unlike convertible notes, SAFEs don’t come with interest rates, maturity dates, or repayment requirements. This means there’s no looming pressure to repay investors if your next funding round gets delayed, keeping your balance sheet clean and stress-free. Joshua Ismin, Co-founder and CEO of Psylo, summed up the appeal of SAFEs in February 2026:
"I was surprised at how quickly a round came together using SAFEs... it just created momentum so much quicker. Using SAFEs... it's like I've had a tougher time getting RSVPs to in-person events than getting investors to sign on because it just made the process templated and quick." – Joshua Ismin, Co-founder & CEO, Psylo
SAFEs are also friendly to founders when it comes to control. They don’t usually grant board seats or interim rights to investors, allowing founders to retain operational authority. Additionally, SAFEs enable rolling closings, meaning you can bring in investors as they commit, rather than coordinating a single closing date. Post-money SAFEs, now the standard, offer predictable dilution. For instance, raising $1 million on a $10 million post-money valuation cap means selling exactly 10% of your company.
This simplicity has made SAFEs a favorite for high-growth startups. In 2018, Notion raised a $10 million seed round using post-money SAFEs to keep their cap table manageable during a critical growth period. Similarly, Dropbox utilized SAFEs during its Y Combinator days to secure funding quickly, letting the team focus on product development instead of legal complexities.
Drawbacks of SAFEs
Despite their advantages, SAFEs come with notable downsides that founders should carefully consider.
One major drawback is the potential for greater founder dilution. Post-money SAFEs, now the market norm, often result in higher dilution compared to convertible notes. This is because the dilution from multiple SAFEs typically falls entirely on the founders rather than being distributed among prior investors. If you issue multiple SAFEs with varying terms, your cap table can quickly become complex, making ownership calculations tricky without specialized tools.
Another issue is the lack of urgency. Since SAFEs don’t have maturity dates, there’s no built-in deadline to push toward a priced round. This can leave startups stuck in "funding limbo", delaying critical next steps in their growth journey.
SAFEs also provide lower liquidation priority. In the event of a company failure, SAFE holders are lower on the repayment hierarchy than convertible note holders, who are treated as creditors and must be repaid first. This makes SAFEs less appealing to certain investors, such as traditional angel investors or regional venture capitalists in markets like the UK, Europe, and Asia, where convertible notes with clearer protections are often preferred.
Lastly, SAFEs convert during any priced equity round, regardless of the amount raised. In contrast, convertible notes often include a "qualified financing" clause, requiring a minimum raise (e.g., $1 million) before triggering conversion. This gives founders more control over when the conversion happens.
These limitations highlight the trade-offs founders must weigh when deciding between SAFEs and other funding instruments like convertible notes.
When to Use Convertible Notes
Best Use Cases for Convertible Notes
Convertible notes are particularly effective when raising funds from institutional investors or traditional venture capitalists (VCs). These types of investors - such as family offices and regional VCs outside Silicon Valley - often lean toward the legal structure and creditor protections that convertible notes offer. Malcolm Tan, a seasoned venture builder, highlights this preference:
"The choice often hinges on who's investing, not just how much. Institutions generally prefer Convertible Notes because of enforceability." – Malcolm Tan, Venture Builder and Founder, Athvision
This approach is especially suited for bridge funding and large funding rounds.
For bridge funding scenarios, convertible notes create a clear timeline with their maturity date, pushing startups to secure a qualifying priced round within 6–12 months. If you need interim financing to achieve specific milestones before a priced equity round, this structure provides the necessary accountability.
Geography also plays a role. In regions like New York, Boston, the UK, Europe, and Asia, convertible notes are more common because SAFEs (Simple Agreements for Future Equity) are not as widely recognized or understood. This preference often extends to industries requiring substantial capital. For larger early-stage rounds - typically $2 million or more - investors tend to favor the explicit protections and defined timelines that convertible notes offer.
Certain industries with longer development timelines, such as biotech, life sciences, hardware, and manufacturing, also frequently use convertible notes. In these sectors, 30–50% of funding rounds rely on this structure because it offers stronger downside protection for investors. For example, Brex, the fintech unicorn, opted for convertible notes during its early rounds to meet the expectations of institutional investors in the highly regulated fintech space.
If your target investors are based on the East Coast or in international markets, convertible notes can streamline the fundraising process. Jason Atkins, President and Co-founder of Cake Equity, described how convertible notes helped his company:
"A convertible note worked well for Cake as we were able to obtain early funding which allowed us to build and grow, while avoiding the delays and complications of a valuation." – Jason Atkins, President & Co-founder, Cake Equity
Ultimately, convertible notes are a strong choice when your startup needs structured, milestone-driven funding, especially when institutional backing and creditor protections are priorities.
When to Use SAFEs
Best Use Cases for SAFEs
SAFEs (Simple Agreements for Future Equity) have become a go-to option for early-stage funding, especially in pre-seed and seed rounds where formal valuations are often unavailable. Data shows that over 95% of pre-seed rounds in Silicon Valley utilize SAFEs, largely because they remove the need to set a valuation while your business metrics are still evolving.
One of the biggest advantages of SAFEs is speed. While convertible notes might take 2–4 weeks to close, SAFEs typically wrap up in just 1–2 weeks. This speed can be a game-changer for maintaining momentum. Joshua Ismin, Co-founder & CEO of Psylo, shared his experience in February 2026:
"Using SAFEs... it just created momentum so much quicker. It's like I've had a tougher time getting RSVPs to in-person events than getting investors to sign on because it just made the process templated and quick." – Joshua Ismin, Co-founder & CEO, Psylo
SAFEs are also widely favored by angel investors, accelerators, and YC-affiliated investors due to their simplicity. With a standardized 1–5 page document, SAFEs are much shorter than the more complex convertible note agreements.
Another benefit? SAFEs don’t show up as debt on your balance sheet. This means they aren’t classified as liabilities, which can help keep your financials clean and improve your debt-to-equity ratios. A clean balance sheet is particularly attractive to Series A investors and can make a big difference in industries like AI, machine learning, consumer apps, and developer tools, where over 90% of startups prefer SAFEs due to rapid growth potential and uncertain early valuations.
The rolling close feature of SAFEs is another plus. Instead of waiting for all investors to commit by a single closing date, you can bring in investors as they commit. However, it’s essential to model dilution carefully. By 2025, 85% of SAFEs issued were post-money, meaning stacking multiple SAFE rounds could lead to unexpected dilution when you reach your Series A.
With their speed, simplicity, and flexibility, SAFEs have become the preferred tool for early funding. This distinction becomes even clearer when compared to convertible notes, as we’ll explore next.
Side-by-Side Comparison: Convertible Notes vs SAFEs
Here's a breakdown of how convertible notes and SAFEs compare across key factors that matter to both founders and investors:
| Feature | Convertible Note | SAFE |
|---|---|---|
| Legal Classification | Debt (Liability) | Equity-like Contract (Not a liability) |
| Interest Accrual | Yes (typically 4–8% in 2026) | No |
| Maturity Date | Yes (typically 18–24 months) | No |
| Repayment Risk | High (investor can demand cash) | None (no repayment obligation) |
| Balance Sheet Impact | Shows as a debt liability | Off-balance sheet or disclosed in a footnote |
| Fundraising Speed | Slower (2–4 weeks) | Faster (1–2 weeks) |
| Legal Costs | $2,000–$5,000 | $0–$1,000 |
| Document Length | 10+ pages | 1–5 pages |
| Investor Appeal | Traditional VCs, family offices, institutional seed funds | Tech angels, accelerators, YC-affiliated investors |
| Liquidation Priority | Senior to SAFEs (creditor status) | Junior to all debt |
| Geographic Preference | ~50% usage in New York and a higher share internationally | 95%+ in Silicon Valley |
| Best For | Bridge rounds, biotech, hardware, large pre-seed ($2M+) | Pre-seed/seed rounds, AI, consumer apps, dev tools |
This comparison highlights the trade-offs founders need to weigh when choosing between these two instruments. While both delay a formal valuation until a priced round, there are distinct differences in cost, risk, and investor preferences.
Convertible notes typically accrue 4–8% annual interest, which increases dilution for founders. SAFEs, on the other hand, skip interest accrual, simplifying the process and reducing complexity. SAFEs also close faster and at a lower cost, thanks to standardized templates, whereas convertible notes require more legal negotiation but provide creditor protections that are often attractive to institutional investors.
Another key distinction is liquidation priority. Convertible note holders enjoy senior status in the event of liquidation, while SAFE holders rank below all debt. As a result, convertible notes may appeal more to investors seeking downside protection.
SAFE vs Convertible Notes: Cap Table Impact
If you want a cleaner view of dilution, a SAFE is usually easier to map. If you want debt-style terms and expect a priced round in 12 to 18 months, a convertible note may fit better.
When I compare the two, the cap table comes down to four things:
- SAFEs don’t accrue interest
- Convertible notes do accrue interest, often 4% to 8% per year
- Post-money SAFEs fix the investor’s target ownership at signing
- Notes can dilute more over time if the next priced round is delayed
That means your choice is not just about legal docs. It changes:
- founder ownership
- employee pool dilution
- investor leverage at maturity
- how easy it is to forecast a Series A
A simple example shows the difference. A $500,000 post-money SAFE at a $5,000,000 cap points to 10% ownership before the next priced round. A $500,000 note at 6% simple interest for 18 months converts as about $545,000, so the final share count grows before conversion.
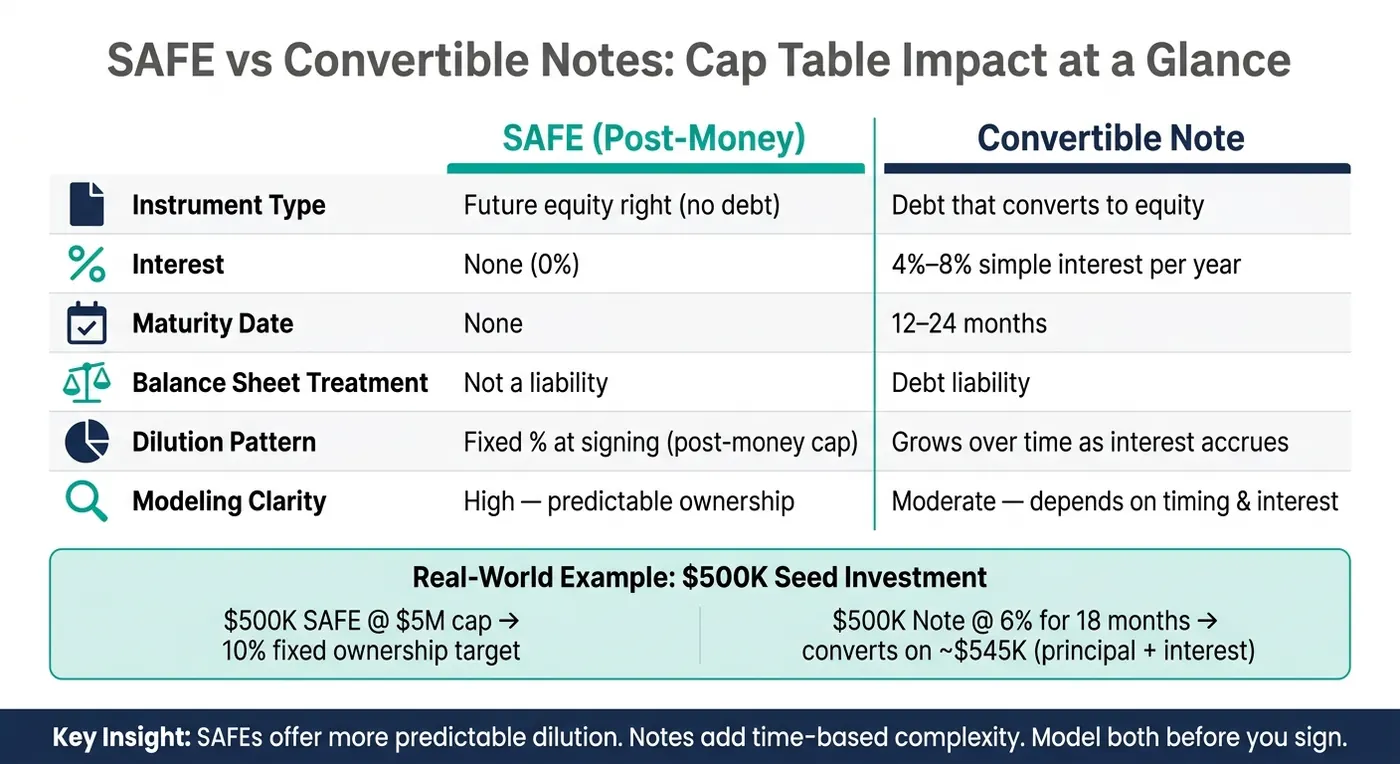
My short take: if you stack multiple SAFEs, founder dilution can pile up fast. If you use notes, interest and maturity can put pressure on both your cap table and your next fundraise. So before you sign, I’d model three cases: a Series A at the cap, above the cap, and below the cap.
How SAFEs Affect Ownership and Dilution
A SAFE is a future equity claim, not debt. Before a priced round closes, it sits off the cap table, which can make dilution easy to miss until conversion. The cap-table effect shows up when the SAFE turns into shares.
Once a priced round closes, each SAFE converts into preferred shares. The total share count goes up, and founder ownership goes down as those once-hidden claims become actual equity.
SAFE Terms That Directly Change the Cap Table
The valuation cap is the term that matters most here. It sets the highest valuation at which the SAFE converts into equity. A lower cap gives the investor more shares at conversion, which means more dilution for founders and employees.
Discount rates - usually between 15% and 25% - let investors convert at a lower price than priced-round investors. If the round is priced below the cap, the SAFE converts at the lower of the cap-based price or the discounted round price.
MFN clauses let early investors match better terms, and pro-rata rights let them keep their ownership in later rounds. Both can make a Series A tougher to structure if they aren't scoped with care when signed.
Pre-Money vs. Post-Money SAFEs: Why the Difference Matters
The big issue is simple: who takes the dilution when several SAFEs stack in the same round?
With a pre-money SAFE, the investor's final ownership percentage isn't fixed until conversion. It changes based on how many other SAFEs are issued in the same round. Earlier investors get diluted by later ones, and the math stays uncertain until the priced round closes.
With a post-money SAFE, the investor's ownership is fixed at signing with a simple formula: Investment ÷ Post-Money Valuation Cap. That gives investors more certainty, but it puts more of the dilution on founders. Each new SAFE check added in the round increases founder dilution, not dilution for earlier investors.
"A post-money SAFE effectively locks in the investor's slice of the pie at the moment of conversion, whereas a pre-money SAFE's ultimate percentage is fluid until your Series A is priced." - Jason Acevedo, Partner, Klehr Harrison
Common SAFE Modeling Mistakes in Seed Rounds
Trouble starts when founders treat each SAFE like its own small deal instead of part of one shared dilution pool.
The biggest mistake is looking at each SAFE on its own. Founders often stack several SAFEs, sometimes with different caps, and assume the dilution will stay under control. A lot of the time, it doesn't.
"The most common founder mistake is 'raising multiple different SAFEs with different terms' rather than running a clean, structured pre-priced layer." - Healy Jones, Kruze Consulting
Another common miss is the option pool shuffle. Series A investors often want the employee option pool increased before the round closes. In post-money structures, that bigger option pool cuts directly into founder ownership.
A third mistake is assuming every SAFE in a round converts on the same economics. Different caps and MFN terms can create uneven conversion math, and that can snowball fast. Patrick Frank can help founders line up SAFE terms in a live cap table and forecast dilution before closing.
How Convertible Notes Affect Ownership and Dilution
A convertible note starts as debt. It stays debt until the company repays it or it converts into equity. That setup creates a timing issue: the longer the note sits out there, the more dilution it can cause later. That's a big reason notes are harder to predict than SAFEs.
Note Terms That Increase Dilution Over Time
Most notes use the same cap-and-discount setup as SAFEs. But they also add simple interest, often 4% to 8% per year. That interest usually isn't paid in cash. Instead, it builds up and converts into extra equity in the next priced round.
"That accrued interest converted into equity. You didn't pay it in cash; it compounded into your cap table." - Seth Girsky, Founder, Inflection CFO
Here's the part founders can miss at first glance: the note doesn't just convert based on the original investment amount. It converts based on the principal plus accrued interest. So at 6% for 18 months, a $1,000,000 note converts as about $1,090,000. That extra $90,000 buys more shares at conversion, which means more dilution than the original check size suggested.
What the Cap Table Looks Like Before Maturity and at Conversion
Before conversion, no new shares are issued. On paper, founder ownership can look unchanged. But that can be misleading. The dilution hasn't disappeared; it's just delayed.
When the note converts, the company takes the full principal plus accrued interest and divides it by the conversion price to get the final share count. That conversion price is the lower of the cap price or the discount price. Until that happens, notes sit on the cap table as liabilities. If the round closes, they convert under their terms, often at the same time as SAFEs.
Risks When the Next Priced Round Is Delayed
This is where notes can get tense. The maturity date is usually 12 to 24 months out. If the company hasn't closed a priced round by then, the investor may demand repayment. For most early-stage startups, that's not a check they can write.
"If the convertible note matures before your Series A closes, you might have to pay it back in cash. That changes everything." - Seth Girsky, Founder, Inflection CFO
And if the round takes longer than planned, the pressure builds from two sides. First, the note balance keeps growing as interest accrues. Second, the investor may gain more leverage if maturity hits before a financing event. At that point, they may push to renegotiate terms or agree to extend maturity on new terms. The longer fundraising drags on, the more interest stacks on top of the original principal, which increases dilution. Those tradeoffs stand out most when you put notes next to SAFEs and compare them directly.
SAFE vs. Convertible Notes: Side-by-Side Cap Table Comparison
Put them next to each other, and the main difference is predictability: SAFEs make future ownership easier to map out, while notes bring in time-based dilution.
SAFEs are cleaner. There’s no interest, no maturity clock, and post-money SAFEs lock in the investor’s target ownership when the deal is signed. Notes come with interest, a maturity date, and extra variables. You can see that gap in four areas: timing, dilution, liabilities, and modeling.
That’s why the next priced round is usually easier to model with SAFEs and harder to forecast with notes.
With post-money SAFEs, the final share count is more predictable. With notes, it turns on accrued interest and the moment of conversion. In a mixed round, even a small shift in conversion timing can change the final cap table.
"The instrument you choose impacts your dilution at Series A, your relationship with investors, your tax complexity, and even your ability to raise future rounds." - CapyTable
Option pool top-ups matter too. Series A investors often ask for an option pool expansion pre-money. With post-money SAFEs, that dilution lands almost entirely on founders - not SAFE holders - because the SAFE’s fixed percentage is calculated without those new shares.
A Hypothetical Dilution Example for a U.S. Seed Round
A $500,000 post-money SAFE at a $5,000,000 cap targets a fixed 10% ownership. At a $20,000,000 Series A, that investor keeps about 8.00% after dilution from the new round.
A $500,000 convertible note with 6% simple interest over 18 months converts on $545,000 in principal plus accrued interest. In that same Series A, the note investor ends up with about 7.08% ownership.
The main takeaway is simple: interest by itself doesn’t mean note holders get more equity. The conversion math matters more.
Choosing the Right Instrument for Cap Table Health
Decision Criteria to Review Before Signing
Once you've compared how each instrument converts, the next step is simple: pick the one that matches your timeline, investor mix, and hiring plan.
The choice usually comes down to five things: how long it may take to reach your next priced round, how many investors you're bringing in, how fast you plan to hire, whether debt pressure is something you can live with, and how clean you want your ownership forecast to look.
| Factor | Favor SAFE | Favor Convertible Note |
|---|---|---|
| Time to Series A | 24+ months or uncertain | 12–18 months with clear milestones |
| Investor count | 10+ small checks | Fewer, larger checks |
| Forecasting clarity | High priority | Comfortable with interest-based dilution |
| Option pool pressure | Low pre-Series A hiring | Hiring plan already scoped |
The hidden variable, more often than not, is the option pool. Model it before you sign anything. Why? Because post-money SAFEs shift that dilution to founders.
It also helps to keep the round simple. Use one cap and one discount across the round so you don't end up with messy conversion mismatches.
Using AI to Maintain a Live Cap Table and Forecast Dilution
After the round structure is in place, keep your cap table live instead of waiting for conversion. A static spreadsheet can work for a while, then fall apart once SAFEs or notes start stacking up.
Update the model every time you add a new instrument. Then run what-if scenarios across Series A prices. That gives you a clearer view of dilution before it shows up on paper.
Conclusion: Choosing the Right Funding Instrument
Deciding between convertible notes and SAFEs depends largely on the type of investors you're targeting, regional practices, and how quickly you need to secure funding.
Here’s how these tools are typically applied: SAFEs are a great fit if you're raising funds from tech angels or accelerators, especially in Silicon Valley. They’re perfect for situations where you need to close funding fast - usually within a week or two - and want to avoid dealing with interest rates or maturity dates. SAFEs are widely used in pre-seed rounds in Silicon Valley because they offer quick closings and straightforward dilution terms. For example, with a post-money SAFE, dilution is crystal clear: raising $1M on a $10M post-money valuation means selling exactly 10% of your company.
On the other hand, convertible notes are better suited for institutional investors, family offices, or East Coast VCs who expect creditor protections and structured terms. They’re also ideal for bridge financing between major funding rounds, as their maturity dates create urgency for raising a Series A. Industries like biotech, hardware, and fintech still rely on convertible notes in about 30% to 50% of early-stage deals.
To ensure you’re making the right choice, use cap table modeling tools to keep seed-stage dilution within the 20%–25% range. It’s also smart to have a startup attorney review the terms, as even standardized documents can include clauses - like side letters or MFN terms - that might complicate your cap table down the road.
"The choice often hinges on who's investing, not just how much. Institutions generally prefer Convertible Notes because of enforceability."Malcolm Tan, Venture Builder
The key takeaway? Match the funding instrument to your investor base, your timeline for a priced round, and your industry’s expectations. When aligned with your startup's specific needs, both SAFEs and convertible notes can be effective tools for raising capital.
A SAFE is cheaper and faster to close, but only a live model shows whether it stays cleaner.
FAQs
How do I estimate dilution from multiple post-money SAFEs?
To figure out dilution from multiple post-money SAFEs, you need to calculate how each SAFE converts into equity during the next funding round. Start by determining the total shares created for each SAFE. This is done by dividing the investment amount of each SAFE by its conversion price, which is based on the valuation cap and the valuation of the upcoming round.
Once you have the number of shares for each SAFE, add them all together. Then, compare this total to the overall number of shares after conversion. This comparison gives you the dilution percentage. Using cap table simulations can make it easier to understand and visualize how these conversions impact ownership percentages.
What happens if my convertible note hits maturity before a priced round?
If your convertible note matures before a priced round occurs, what happens next hinges on the terms in your agreement. Typically, there are three main paths forward:
- Convert the note into equity: The note may convert into equity at a pre-determined valuation or discount.
- Extend the maturity date: The parties might agree to push the maturity date further out, giving more time for a priced round to happen.
- Repay the note: In some cases, the noteholder may require repayment of the principal and any accrued interest.
It's crucial to carefully review your agreement to understand the specific options and obligations tied to your situation.
Can I mix SAFEs and convertible notes in the same raise?
Yes, it's possible to mix SAFEs (Simple Agreements for Future Equity) and convertible notes within the same fundraising round. This strategy allows startups to accommodate varying investor preferences.
Some investors lean toward SAFEs due to their simplicity and founder-friendly structure. On the other hand, others may prefer convertible notes because they function as debt instruments, offering interest and maturity terms. However, convertible notes can introduce additional complexity to the cap table compared to SAFEs, which are generally quicker to execute.
By offering both options, startups can appeal to a broader range of investors while balancing the pros and cons of each instrument.
How do stacked SAFEs affect founder dilution?
Stacked SAFEs can create a compounding dilution effect that's often bigger than it looks when you sign each one. Here's why: post-money SAFEs lock in ownership at signing, so every new SAFE adds dilution that shows up on the cap table later, all at once, in a future priced round.
With staggered SAFEs, total dilution equals the combined ownership impact of each SAFE. If you want to avoid a nasty surprise, model all stacked instruments together on a fully diluted basis before your next financing round.
When does a convertible note become risky?
A convertible note gets risky when you don’t close a priced equity round before the maturity date. Since it’s a debt instrument, the company may have a legal duty to repay the principal plus accrued interest once that date passes.
That deadline can also shift power toward investors. They may use it to press for repayment, force conversion, or negotiate terms that work against the company. And while all of that is happening, interest keeps adding up, which means any later conversion can turn into more equity than you planned to give away.
How should I model option pool top-ups?
Run your fully diluted cap table through a few likely conversion scenarios before you sign anything. SAFE and convertible note conversions can change dilution in ways that aren’t obvious at first glance, so it helps to compare how pre-money, post-money, and dollars-invested methods change ownership.
The final share count can move around based on the terms of the priced round, especially if you adjust the option pool right before closing. That one change can hit founder ownership harder than people expect.
The main job here is simple: focus on the levers that most change later ownership. Then use cap table software to model those scenarios ahead of time, so you don’t get blindsided by surprise dilution.